Lot No. LOT-8222 · offered November 6, 2026
Ag Finance & InvestmentLot sheet
ADM Raises 2026 EPS Outlook to $5.50-$5.80 After Q3 Profit Jump
ADM posted Q3 2026 net earnings of $821 million, adjusted EPS of $1.77, and lifted full-year guidance to $5.50-$5.80 on biofuel-driven crushing and ethanol strength.
Market notes
- ADM raised 2026 adjusted EPS guidance to $5.50-$5.80 from $5.15-$5.60.
- Q3 net earnings were $821 million; adjusted EPS of $1.77 rose $0.85 year over year.
- Total segment operating profit hit $1.4 billion versus $845 million a year earlier.
- Crushing operating profit increased $298 million on North American biofuel margins after March RVO finalization.
- Capital expenditure guidance was cut to $1.2-1.3 billion from $1.3-1.5 billion.
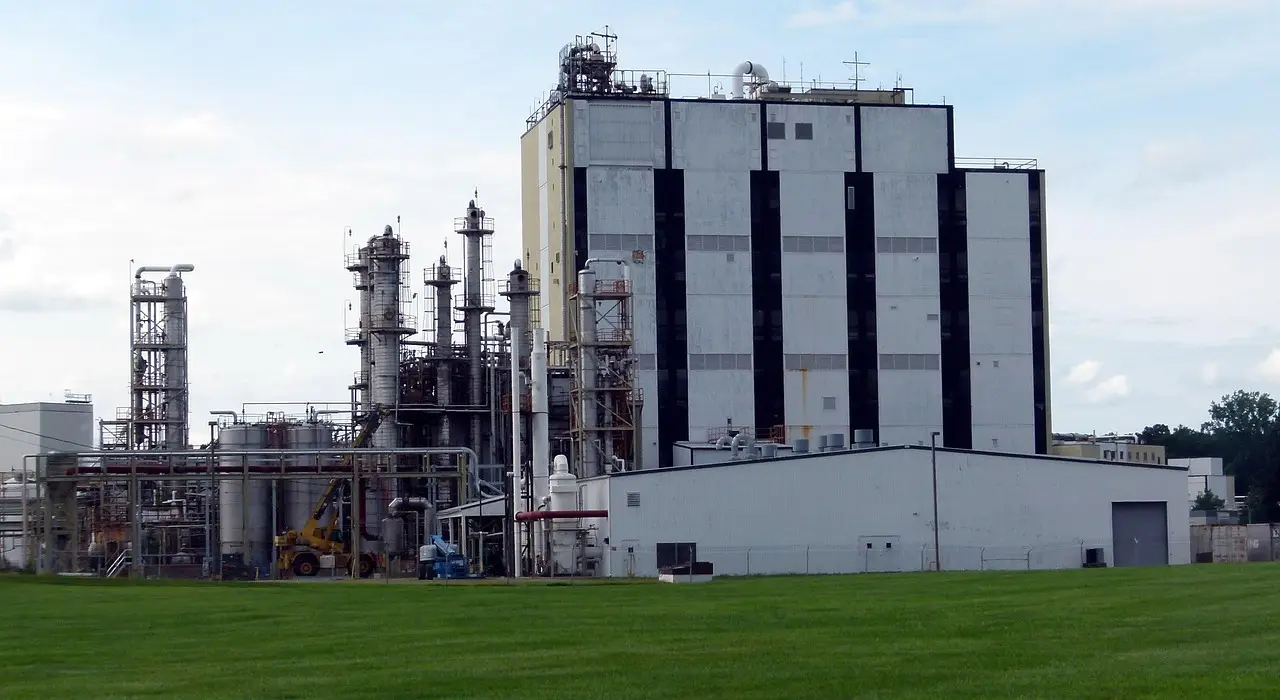
ADM reported third-quarter 2026 net earnings of $821 million and adjusted EPS of $1.77, up $0.85 from $0.92 a year earlier, and raised its full-year adjusted EPS guidance to $5.50-$5.80 from $5.15-$5.60.
The quarter, ended Sept. 30, delivered GAAP EPS of $1.70, a $1.48 increase over the prior-year quarter's $0.22. Earnings before income taxes hit $997 million against $147 million a year ago. Total segment operating profit reached $1.4 billion, compared with $845 million in the prior-year quarter, excluding $36 million in net specified item charges.
"ADM delivered strong third-quarter results, with earnings up significantly from the prior-year quarter and operating profit growth across all segments," said Juan Luciano, chair of the board and chief executive officer. "These results were driven by a constructive biofuels environment combined with our extensive North American footprint, which gives us significant access to premium markets, and good execution by our team."
Luciano added that year-to-date performance and the fourth-quarter outlook support another increase to full-year 2026 adjusted EPS guidance.
What drove the upgrade?
All segments posted operating profit growth, and ADM expects that pattern to hold in the fourth quarter. Year-to-date earnings before income taxes stand at $2.5 billion versus $779 million in the prior-year period. Total segment operating profit reached $3.6 billion year to date, up from $2.4 billion. GAAP EPS is $4.18 year to date, up $2.89; adjusted EPS is $4.33, up $1.77.
Capital expenditures were cut to a projected $1.2-1.3 billion from the prior $1.3-1.5 billion range. ADM said the revision reflects continued prioritization of high-return investments. The company continues to monitor macroeconomic, geopolitical, policy and trade conditions.
Where did segment profits land?
- Ag Services and Oilseeds: $778 million, up 105% year over year, including roughly $35 million of net positive mark-to-market and timing impacts.
- Carbohydrate Solutions: $470 million, up 40%.
- Nutrition: $134 million, up 3%.
Within AS&O, Ag Services operating profit fell 9% on weaker results in certain global supply chain markets, with higher North American corn and soybean exports partially offsetting the decline. Crushing operating profit rose $298 million on a constructive North American biofuel margin environment, which the company ties to domestic demand from the renewable volume obligation policy finalized in March plus higher global energy prices. Global crush production volumes rose 1.6% year over year, and soybean meal demand stayed strong. Brazilian crush margins remained pressured by delays in that country's biofuels policy changes.
Refined Products and Other operating profit jumped 82%, largely on favorable North American biodiesel margins, including mark-to-market and timing impacts of roughly $45 million positive. Equity earnings from the Wilmar investment ran about 38% higher than a year ago.
How did ethanol and nutrition perform?
Starches and Sweeteners operating profit gained 11%, as strong ethanol margins including policy incentives more than offset softness in liquid sweetener margins and volumes. Starches stayed stable and global wheat milling volumes held flat in a competitive pricing environment. Vantage Corn Processors added $103 million in operating profit year over year, driven by robust North American ethanol margins, policy incentives, higher domestic demand and strong industry-wide exports.
Human Nutrition operating profit slipped 3%. Progress in Flavors and the recovery of the Decatur East plant were more than offset by unplanned downtime, inflation in certain input costs, softness in Biotics, and a roughly $10 million insurance-proceeds benefit in the prior-year quarter. Animal Nutrition rose 21% on operational improvements and benefits from 2025 portfolio actions.
Corporate results improved because prior-year impairment losses did not recur. Other Business gained from a one-time benefit tied to the release of certain insurance reserves.
With all three segments guiding to further profit improvement in the fourth quarter and capex tightened toward high-return projects, ADM enters the close of 2026 positioned to test the top of its raised $5.50-$5.80 adjusted EPS range.
via Feedstuffs (Source)
More from Grace Kim
Show full bio
Correspondent covering people, launches and day-to-day practice in Agribusiness coverage for industry professionals at Agribusiness Wire.
464 articles
Also in the yard
- Mahindra Farm Equipment Revenue Up 0.6% Despite Tractor Slump
- Deere Leads Agricultural Machinery Stocks in Q2 Earnings Beats
- Analyst Outlook Points to Corn Price Surge in 2027 for U.S. Growers
- CHS nearly doubles net income to $1.1B in fiscal 2026
- PPI Posts 6.3% Annual Gain as Diesel Doubles, Pressuring Farm Margins